AI reaches beyond technology shares
US growth remains supported by business investment, which has broadened beyond AI, and continued household consumption. Our central scenario still assumes growth close to potential next year. The scale of AI spending nevertheless makes its trajectory consequential for the wider economy. Slower construction would affect equipment orders and infrastructure suppliers before its full implications appeared in aggregate growth.
Consumption provides a second connection. Rising wealth has helped households sustain spending despite subdued real income gains. A prolonged market correction could weaken that support, although our economic analysis suggests the wealth effect is smaller than some estimates imply. This adds a vulnerability without, at this stage, overturning the expansion scenario.
The same dependence runs through equity markets. US technology companies finance and operate the infrastructure; Asian semiconductor and memory suppliers earn revenues from equipping it. Industrial businesses provide power equipment and other scarce capacity. Holding these exposures across several regions does not necessarily spread the underlying investment risk.
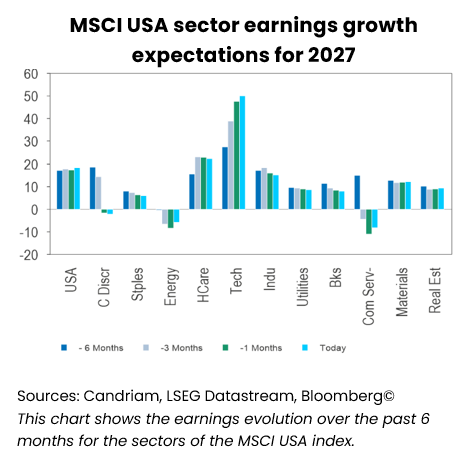
Having said that, we note that Technology profit forecasts remain strong. The Q3 evidence also gives little support to a collapse in operating demand: 76% of reporting S&P 500 companies beat earnings expectations. Yet US technology companies that beat earnings estimates underperformed the market by an average 1.8% the following day. Good current results have offered limited protection against concerns further ahead.
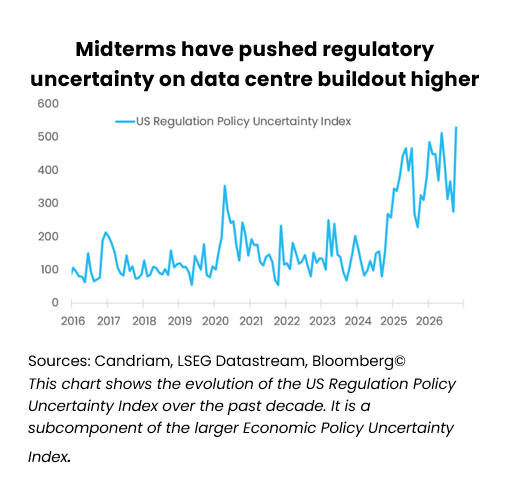
The midterms have made the timing of data centre investment more difficult to assess
With key states turning blue at the national level, and many also at the state level, policy has become a central concern for technology companies planning AI data centres. Approvals and protections for electricity consumers can change project locations, power connection dates and who pays for infrastructure. Much of the near-term pipeline is already under construction; investment planned for 2028 and beyond is more exposed to delays or relocation.
Agreements to fund power infrastructure and protect local users could allow projects to proceed under revised terms. Our central scenario still assumes investment continues. We will watch whether negotiations mainly alter costs and locations or reduce total spending, which would pose a greater threat to semiconductor demand.
Financing extends this exposure into credit portfolios. Spending increasingly draws on debt, leases and outside capital alongside operating cash flow. Investors need to assess whether issuers can fund construction and generate revenues before equipment replacement or refinancing becomes necessary.
Low multiples and high expectations
The sell-off has reduced valuations while cloud revenues, semiconductor orders and management spending plans continue to indicate strong demand. Regulatory risks help explain the gap: delays defer revenues, infrastructure commitments raise capital requirements, and less predictable rules increase the return investors demand. Strong current earnings can therefore coexist with lower valuations.
These pressures reinforce the case for selection. Integrated businesses with established customers and several sources of cash generation are better placed to absorb delays than operators reliant on external financing. For developers and suppliers alike, the timing and cost of investment matter alongside its scale.
Korea illustrates why valuation requires care. Its low forward multiples sit alongside exceptionally high forecast earnings, with consensus already anticipating a decline after 2028. The price investors should pay depends on how much of that profitability survives beyond the spending surge. A multiple calculated on unusually strong profits can exaggerate the apparent discount.
Overall, we retain our preferences for Japan and emerging markets, alongside the US. The case for Technology over the coming months rests on operating demand and the price paid for earnings. Healthcare’s sharp rally has, meanwhile, reduced the appeal of adding defensive exposure at current valuations.
Japan combines exposure to investment with domestic fiscal support. Within emerging markets, we are gaining confidence in selected Chinese equities after their underperformance, while weak domestic demand still argues for selectivity. China offers a different starting valuation, and earnings mix from the semiconductor-heavy markets, without requiring us to assume a broad consumer recovery.
Balance the common exposure
Europe’s earnings have exceeded expectations, including outside Financials and Energy. Its energy sensitivity and political and fiscal constraints still justify a neutral regional equity stance. We retain selective exposure to industrial investment beneficiaries, while assessing their overlap with technology holdings elsewhere in the portfolio.
Our slight equity overweight therefore combines confidence in continued earnings growth with selectivity about its sources. A data centre delay can defer orders for suppliers while easing the immediate funding burden on the company commissioning it. Exposure to the same investment programme does not imply the same financial consequences.
Credit spreads have widened, giving us greater confidence in selected opportunities. Compensation still varies considerably by issuer, particularly where financing needs are rising. Our multi-asset allocation remains neutral on investment grade and European high yield, cautious on US high yield, and positive on emerging-market local-currency debt.
A sound borrower does not automatically offer an attractive bond, and strong operating results can coexist with heavy issuance and rising capital requirement. As a consequence, we look for compensation for those financing demands and balance sheets able to withstand delays.
Duration has a role again
Lower yields have two explanations relevant to portfolios. Falling crude prices have reduced inflation expectations and the amount of policy tightening priced by markets. Concerns about AI investment have also weighed on expected growth and real yields. Government bonds have consequently provided protection during equity weakness.
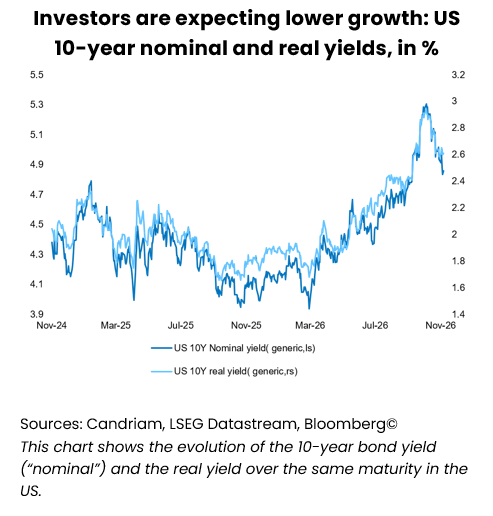
Inflation remains a constraint. Labour market strength, uncertainty about the geopolitical influence on the price of oil and elevated underlying inflation leave room for further Fed tightening. In Europe, cheaper crude has not removed refining constraints or pressure from gas and electricity prices ahead of winter. Another energy shock could push bonds and equities lower together.
Financial conditions also influence how far central banks need to go. Higher borrowing costs and weaker equities already restrain demand, giving policymakers reasons to assess their transmission before tightening much further. A limited hiking cycle, including one hike in December and another one in 2027, remains compatible with our investment stance.
We maintain our preference for core European duration within a neutral overall bond allocation. Tighter financing conditions and modest regional growth support that position. Fiscal credibility determines which sovereign debt provides protection: we remain cautious towards weaker public finances, including France and Belgium. German support for activity does not remove those differences.
Gold and liquid alternative strategies remain complementary diversifiers. Alongside core duration, they help diversifying from an equity allocation whose regional and sector exposures can depend on common spending decisions. That being said, with US 10-year yields above 5.0%, upward pressure on the US dollar, and higher volatility of the price of Gold, we have somewhat reduced our exposure towards precious metals in recent weeks. Regarding equities, we would reduce risk if project delays became widespread cancellations or profit guidance deteriorated materially. For now, earnings and investment commitments support retaining our slight overweight, with duration providing a useful counterweight as long as inflation allows yields to respond to weaker growth.


